Osceola County, Michigan

Above the national median for unemployment (average of monthly rates) — and 11.4× the rate of the healthiest U.S. county (Loving County, TX — 1%).
Main Findings
Osceola County, Michigan is more distressed than 78% of U.S. counties on the County Distress Index. The driver: 6% of the labor force was unemployed on average from September 2025 to August 2026 — above the national median of 4%. Its highest-scoring domain is Labor and its lowest is Default & Legal.
- 7th of 83 counties in Michigan on the County Distress Index — 78 · high county distress, more distressed than 78% of U.S. counties.
- 6% of the labor force was unemployed on average from September 2025 to August 2026 (U.S. median 4%). Unemployment (average of monthly rates) at the 93rd percentile nationally. Source: U.S. Bureau of Labor Statistics, LAUS (monthly rates averaged, September 2025 to August 2026; no figures published for October 2025).
- Disability rate at 19% — national median 16%, ranked at the 75th percentile. Source: U.S. Census Bureau, ACS 5-year (2024).
- Auto loan delinquency at 7% — national median 5%, ranked at the 77th percentile. Source: Urban Institute Debt in America (2025).
- Rent-to-income ratio at 23% — national median 21%, ranked at the 71st percentile. Source: U.S. Department of Housing and Urban Development Fair Market Rents (FY2027); U.S. Census Bureau, SAIPE (2024).
Neighbors span four CDI score labels. The 41-point drop to Missaukee County marks where the Michigan distress corridor ends.
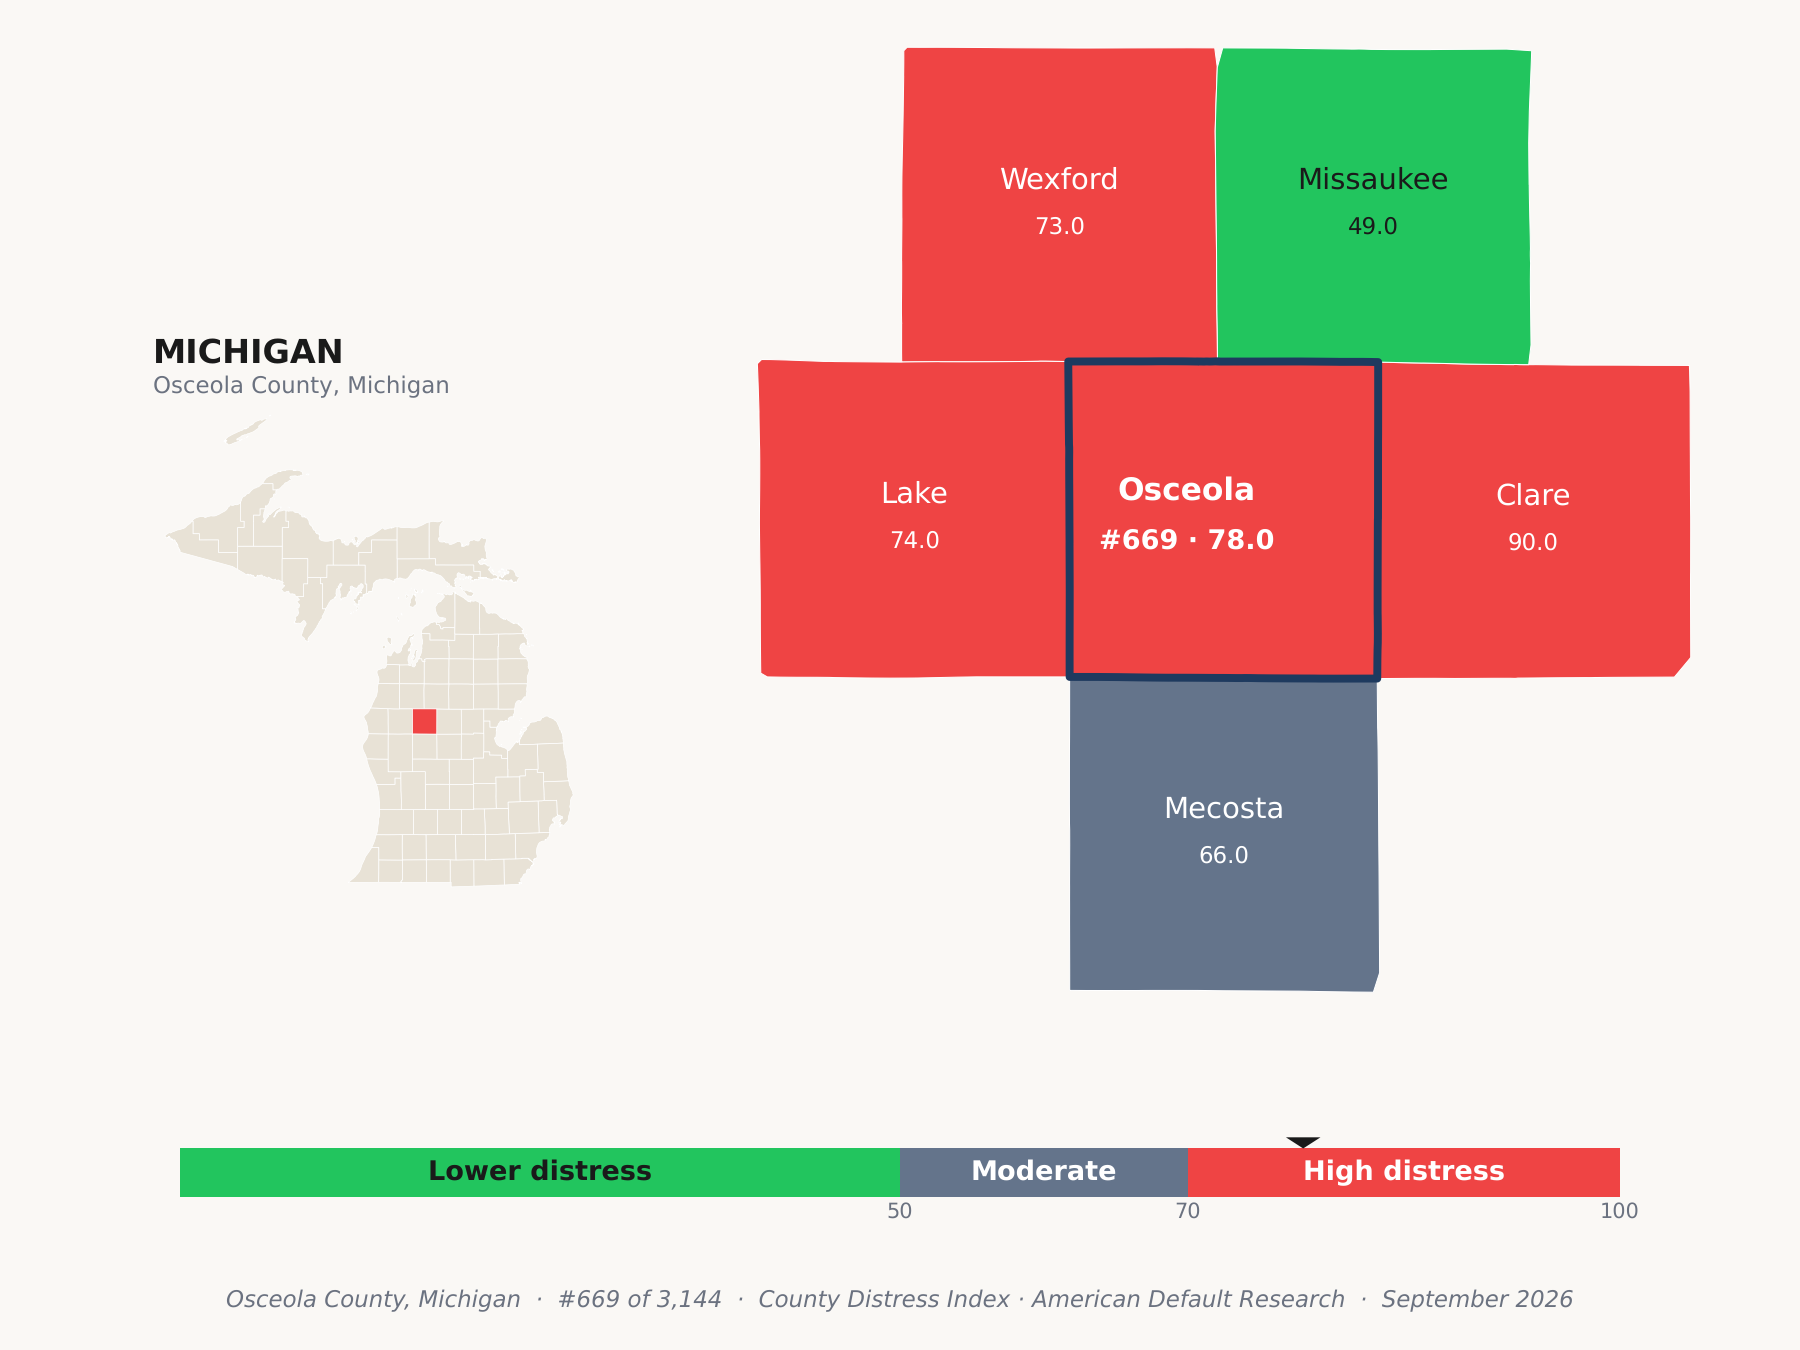
Osceola County has a high county distress score. The score label gives the intensity; the rank gives the national position.
The CDI gives this county a high county distress label. The rank belongs beside the score because the two answer different questions: score intensity and national position. Its highest-scoring domain is Labor.
Indicator History
Period-correct raw indicators from the county-history panel. The CDI composite is excluded because it is a current cross-sectional score.
Unemployment rate
Poverty rate
Transfer income share
Subprime credit population
The Indicators Behind Osceola County's CDI Score
Every number traces to a public source. Osceola County's value shown alongside MI's median and the U.S. median. Full CSV available for download.
| Indicator | Osceola | MI median | U.S. median | Pctile | Source |
|---|---|---|---|---|---|
| Delinquency — domain score 65 · Rank 1,028 of 3,144 | |||||
| Auto loan delinquency Share of auto loan accounts 60+ days past due | 7% | 4% | 5% | 77th | Urban Institute Debt in America (2025) |
| Credit card delinquency Share of credit card accounts 60+ days past due | 7% | 5% | 5% | 67th | Urban Institute Debt in America (2025) |
| Subprime credit share Share of residents with a credit score below 660 | 24% | 19% | 23% | 51st | Equifax data retrieved via FRED (2025) |
| Default & Legal — domain score 49 · Rank 1,585 of 3,144 | |||||
| Debt in collections Share of residents with a credit file who have debt in collections | 26% | 20% | 23% | 59th | Urban Institute Debt in America (2025) |
| Bankruptcy filing rate Personal bankruptcy filings per 100,000 residents | 107 | 114 | 126 | 40th | Administrative Office of the U.S. Courts, F-5A (2025) |
| Debt Burden (housing basis) — domain score 62 · Rank 992 of 3,144 | |||||
| Rent-to-income ratio Fair Market Rent (2BR) as share of median household income | 23% | 21% | 21% | 71st | U.S. Department of Housing and Urban Development Fair Market Rents (FY2027); U.S. Census Bureau, SAIPE (2024) |
| Severe rent burden (50%+) Share of renter households paying 50%+ of income on rent | 19% | 20% | 18% | 53rd | U.S. Census Bureau, ACS 5-year (2024) |
| Labor — domain score 88 · Rank 206 of 3,144 | |||||
| Adults 25-54 not working Share of adults aged 25 to 54 without a job, leaving out residents of prisons and other institutions (service members count as working) | 28% | 22% | 21% | 84th | U.S. Census Bureau, ACS 5-year (2024) |
| Unemployment (average of monthly rates) Share of labor force unemployed, averaged over the monthly rates published for September 2025 to August 2026 (no figures published for October 2025) | 6% | 5% | 4% | 93rd | U.S. Bureau of Labor Statistics, LAUS (monthly rates averaged, September 2025 to August 2026; no figures published for October 2025) |
| Safety Net & Buffer — domain score 71 · Rank 755 of 3,144 | |||||
| Child poverty rate Share of children under 18 below the federal poverty line | 21% | 17% | 17% | 67th | U.S. Census Bureau, SAIPE (2024) |
| Disability rate Share of residents reporting a disability | 19% | 17% | 16% | 75th | U.S. Census Bureau, ACS 5-year (2024) |
| Poverty rate Share of population below the federal poverty line | 16% | 13% | 13% | 68th | U.S. Census Bureau, SAIPE (2024) |
| Uninsured rate Share of residents without health insurance coverage | 9% | 5% | 8% | 61st | U.S. Census Bureau, ACS 5-year (2024) |
Five-Domain Breakdown
The CDI is an equal-weight composite of five family-v1 distress domains. Each domain contributes 20% of the county score.
Methodology
The County Distress Index scores household financial distress from 0 to 100 for all 3,144 U.S. counties. A county's score is the share of U.S. counties it is more distressed than. The index is built from five equal-weighted domains: Delinquency, Default & Legal, Debt Burden, Labor, and Safety Net & Buffer. Each domain is the mean of distress-oriented indicator percentiles; the five domains are averaged, and that average is ranked against every other county to give the score.
Data sources include the Urban Institute Debt in America (Equifax consumer credit panel), Equifax data retrieved via FRED (subprime credit share), U.S. Census Bureau (American Community Survey 5-year, Small Area Income and Poverty Estimates), U.S. Bureau of Labor Statistics (Local Area Unemployment Statistics), Administrative Office of the U.S. Courts (F-5A bankruptcy filings), and U.S. Department of Housing and Urban Development Fair Market Rents. Data vintages range from 2024 to 2027 depending on source; full indicator-level vintage detail is in the methodology document.
For Press & Research
Everything you need to cite Osceola County data.
Draft wire copy 133-word AP-style article — use freely with attribution
REED CITY, Mich. — Osceola County is more distressed than 78% of U.S. counties, according to the County Distress Index released this month by American Default Research.
Osceola scores 78 out of 100, which means it is more distressed than 78% of U.S. counties; its score label is high county distress. Within Michigan, Osceola ranks seventh of 83 counties.
The index, which draws on 14 source indicators from the U.S. Census Bureau, Bureau of Labor Statistics, Urban Institute and federal court filings, identifies labor as the primary driver in Osceola. 6% of the labor force was unemployed on average from September 2025 to August 2026 — above the national median of 4%.
American Default Research founder Ross Kilburn is available for interview at press@americandefault.org.
Full methodology and county-by-county data are available at americandefault.org/methodology/cdi.
Frequently Asked Questions
What is Osceola County's CDI score, and what does it mean?
What drives Osceola County's distress score?
How does Osceola County compare to its neighbors?
How is the County Distress Index calculated?
Osceola County resident looking for help? HUD counselors, legal aid, and attorney referrals →