Foreclosure Prevention Actions Completed, Fannie Mae and Freddie Mac Loans
Workouts Fannie Mae and Freddie Mac completed each month for borrowers who were behind or at risk of default
What is the current Foreclosure Prevention Actions Completed, Fannie Mae and Freddie Mac Loans reading?
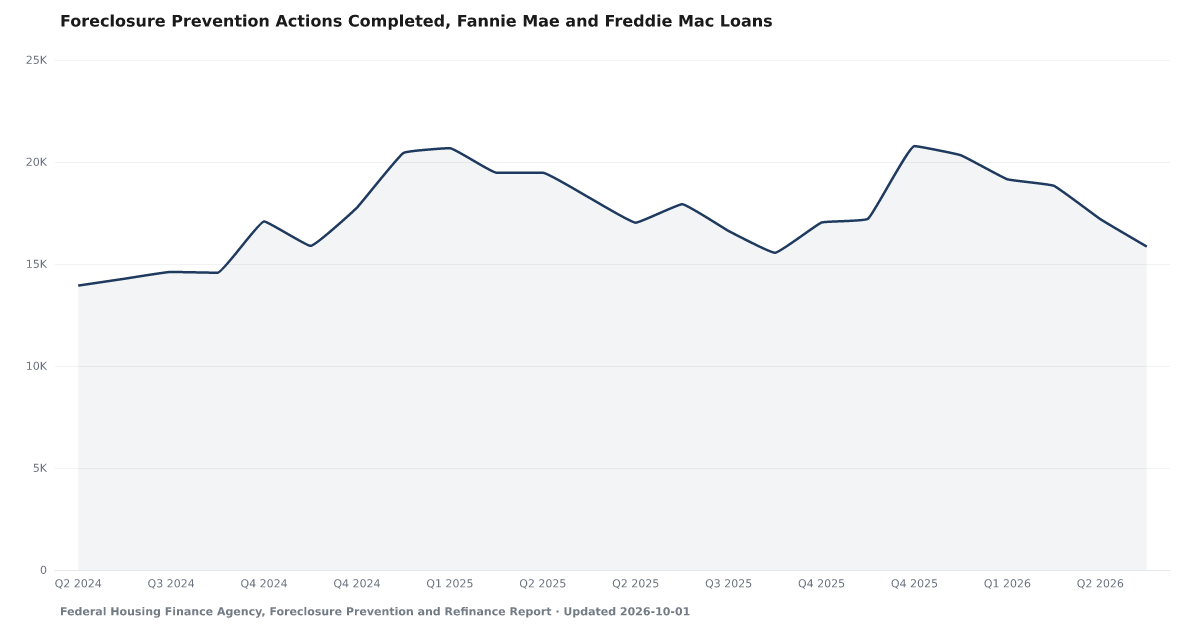
Fannie Mae and Freddie Mac completed 15,855 foreclosure prevention actions in May 2026, 2,395 fewer than a year earlier. The total counts every workout for borrowers who were behind or at risk of default, from loan modifications, repayment plans and payment deferrals to short sales and deeds-in-lieu. It covers only the two companies' single-family loans. Source: Federal Housing Finance Agency, Foreclosure Prevention and Refinance Report.
Measurement basis: Total foreclosure prevention actions Fannie Mae and Freddie Mac completed in the calendar month (FHFA: Completed, TOTAL): home retention actions (loan modifications, repayment plans, forbearance plans, charge-offs in lieu of foreclosure and payment deferrals) plus home forfeiture actions (short sales and deeds-in-lieu). A monthly count of actions, not of borrowers, from the Highlights page of FHFA's Foreclosure Prevention and Refinance Report. FHFA's quarterly editions print only quarter totals, which are never used as a month; a month with no monthly figure is left out.
Fannie Mae and Freddie Mac completed 15,855 foreclosure prevention actions in May 2026, 2,395 fewer than a year earlier.
The Federal Housing Finance Agency adds up every workout Fannie Mae and Freddie Mac complete in a month for borrowers who are behind or at risk of default and calls the total foreclosure prevention actions. In May 2026 the total was 15,855, down from 18,250 in May 2025.
The total has two parts. Home retention actions let the borrower stay in the home: loan modifications, repayment plans, forbearance plans, payment deferrals and charge-offs in lieu of foreclosure. Home forfeiture actions, short sales and deeds-in-lieu, end with the borrower giving up the home without a foreclosure sale.
A bigger total can mean more borrowers got help, or that more of them needed it. It covers only single-family loans that Fannie Mae or Freddie Mac own or guarantee. For the modifications alone, see Loan Modifications Completed, Fannie Mae and Freddie Mac Loans. FHFA's quarterly editions print only three-month totals, so a month that no monthly edition covers is left out of the chart rather than estimated from the quarter.
Explore Further
Foreclosure Prevention Actions Completed, Fannie Mae and Freddie Mac Loans over time: what has changed?

Counties with the highest delinquency scores
These are delinquency scores from our County Distress Index, not county readings of Foreclosure Prevention Actions Completed, Fannie Mae and Freddie Mac Loans.
Explore all 3,144 counties →| Period | Value | YoY Change |
|---|---|---|
| May 2026 | 16K | -2K |
| Apr 2026 | 17K | -2K |
| Mar 2026 | 19K | 0 |
| Feb 2026 | 19K | -2K |
| Jan 2026 | 20K | 0 |
| Dec 2025 | 21K | +3K |
| Nov 2025 | 17K | +1K |
| Oct 2025 | 17K | 0 |
| Sep 2025 | 16K | +1K |
| Aug 2025 | 17K | +2K |
| Jul 2025 | 18K | +4K |
| Jun 2025 | 17K | +3K |
Frequently Asked Questions
What counts as a foreclosure prevention action?
Any workout Fannie Mae or Freddie Mac completes for borrowers who are behind or at risk of default: a loan modification, repayment plan, forbearance plan, payment deferral or charge-off in lieu of foreclosure, which let the borrower stay in the home, or a short sale or deed-in-lieu, where the borrower gives the home up without a foreclosure sale.
Does a bigger total mean more households are in trouble?
Not on its own. A bigger total can mean more borrowers got help or that more needed it. Read it beside the serious delinquency rate and foreclosure starts on the same loans.
Why is a month missing from the chart?
FHFA's quarterly editions print only three-month totals, so a month that no monthly edition covers is left out of the chart rather than estimated from the quarter.
Where does this data come from?
The Federal Housing Finance Agency's Foreclosure Prevention and Refinance Report, which FHFA publishes as a PDF with no release calendar: a monthly edition for eight months of the year and a quarterly edition for March, June, September and December. We read the Highlights table of each new edition with an automated parser and check every number against the PDF's own text before it is saved.

Quick poll
Is this affecting you or your household?
Discussion
Get the numbers when they move.
New data drops, indicator updates, and American Distress Index changes — delivered when it matters. No spam.
or Create an Account for full access
Loading comments…