Total Delinquency Rate (All Loan Types)
Also tracked as Falling Behind
Share of debt balances on credit reports in some stage of delinquency
What is the current Total Delinquency Rate (All Loan Types) reading?
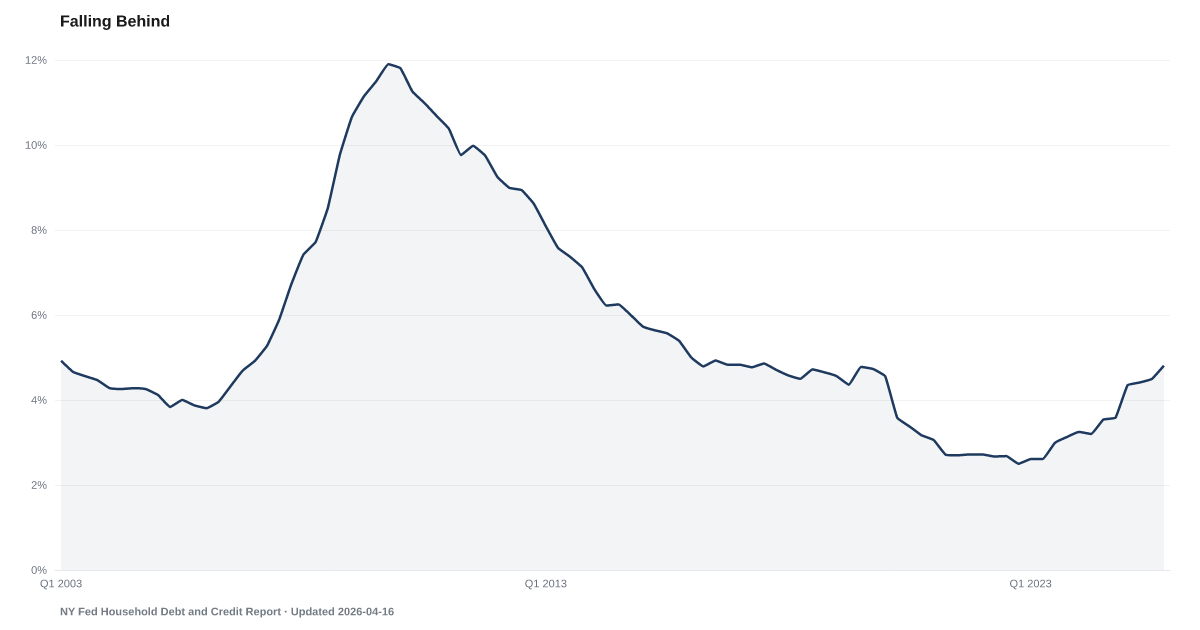
In Q2 2026, 4.7% of consumer debt balances on credit reports were 30 or more days past due, up from 4.4% a year earlier, according to the Federal Reserve Bank of New York. The measure covers mortgages, home equity lines, auto loans, credit cards, student loans and other consumer loans, and it counts dollars, not people. Source: Federal Reserve Bank of New York Household Debt and Credit Report.
The share of debt on U.S. credit reports 30 or more days late was 4.7% in Q2 2026, up from 4.4% a year earlier.
The New York Fed's Household Debt and Credit Report put the share of consumer debt balances in some stage of delinquency at 4.7% in Q2 2026, up from 4.4% a year earlier. It edged down from 4.8% in Q1 2026, a small move in a series that is not seasonally adjusted.
The share counts every balance 30 or more days late, from debt a month or two behind to balances marked severely derogatory: tied to a repossession, charge-off or foreclosure that lenders still report. In Q2 2026 that severely derogatory part was about two-fifths of the total. It is a share of dollars, not of people, across mortgages, home equity lines, auto loans, credit cards, student loans and other consumer loans. Medical bills, and debts lenders do not report to the credit bureaus, are outside it.
Changes in student-loan reporting split this series into separate stretches. In 2012 previously unreported defaulted student loans were added to credit reports. From 2020 paused federal loans were reported as current, and accounts in pandemic forbearance typically were too. Missed federal student loan payments began appearing on credit reports again in the first quarter of 2025, so the comparisons on this page start there. They leave out the fourth quarter of 2025, when the New York Fed carried over the prior quarter's status for about one million student-loan borrowers whose loans were transferred to the Education Department. The New York Fed also says gaps in reporting when mortgages changed servicers affected mortgage balances in the fourth quarter of 2024 and the second quarter of 2026.
Before the 2025 student-loan reporting change: at the end of 2019, before the pandemic, the share was 4.7%. At the end of 2009, during the housing crisis, it was 11.9%.
Serious Delinquency is the narrower measure from the same report: only balances 90 or more days late. Rates for loans held by banks, such as Credit Card Delinquency, come from the Board of Governors of the Federal Reserve System's bank reports and drop balances once they are charged off, so their levels are not comparable with this share.
Explore Further
Is this happening to you?
Have you missed a payment or fallen behind on any bill in the past year?
Total Delinquency Rate (All Loan Types) over time: what has changed?

Counties with the highest delinquency scores
These are delinquency scores from our County Distress Index, not county readings of Total Delinquency Rate (All Loan Types).
Explore all 3,144 counties →| Period | Value | YoY Change |
|---|---|---|
| Q2 2026 | 4.7% | +0.3 pp |
| Q1 2026 | 4.8% | +0.5 pp |
| Q4 2025 | 4.8% | — |
| Q3 2025 | 4.5% | — |
| Q2 2025 | 4.4% | — |
| Q1 2025 | 4.3% | — |
| Q4 2024 | 3.6% | +0.5 pp |
| Q3 2024 | 3.5% | +0.5 pp |
| Q2 2024 | 3.2% | +0.6 pp |
| Q1 2024 | 3.3% | +0.7 pp |
| Q4 2023 | 3.1% | +0.6 pp |
| Q3 2023 | 3% | — |
How to read this series
The source changed how it measures this in Q3 2012. The New York Fed says previously unreported defaulted student loans reappeared on credit reports in the third quarter of 2012, entering both the late balances and the total, so the student-loan part of this share is not measured the same way on either side of that quarter. Readings on either side are not directly comparable, so the year-over-year column stays blank where a comparison would cross that date. Source documentation.
The source changed how it measures this in Q2 2020. From the second quarter of 2020 federal student loans in the pandemic payment pause were reported as current, and the New York Fed said accounts in forbearance were typically reported current on credit reports. Readings on either side are not directly comparable, so the year-over-year column stays blank where a comparison would cross that date. Source documentation.
The source changed how it measures this in Q4 2022. In the fourth quarter of 2022 the Education Department's Fresh Start program marked more than $34 billion of defaulted federal student loans as current, which the New York Fed tied to that quarter's drop in reported student-loan delinquency. Readings on either side are not directly comparable, so the year-over-year column stays blank where a comparison would cross that date. Source documentation.
The source changed how it measures this in Q1 2025. In the first quarter of 2025 the New York Fed says missed federal student loan payments from the pause period began appearing on credit reports again, so readings from then on are not on the same footing as 2020 through 2024. Readings on either side are not directly comparable, so the year-over-year column stays blank where a comparison would cross that date. Source documentation.
Frequently Asked Questions
What share of U.S. household debt is delinquent?
The New York Fed counts 4.7% of the debt on credit reports as being in some stage of delinquency in Q2 2026, up from 4.4% a year earlier. That takes in anything 30 or more days late, including charged-off debt lenders still report.
Is this the share of people who are behind on their debts?
No. It is a share of dollar balances, so one large late mortgage counts for more than many small late card balances. People without a credit report are outside it.
What happened to the rate in early 2025?
In the first quarter of 2025, missed federal student loan payments from the pandemic pause began appearing on credit reports again after nearly five years. The New York Fed attributes the change in student-loan delinquency to those payments newly showing up, not to a single quarter of new missed payments.
Where does the total delinquency data come from?
The Federal Reserve Bank of New York's Quarterly Report on Household Debt and Credit, built from a random sample of anonymized Equifax credit reports. It comes out about six weeks after each quarter ends.


Quick poll
Is this affecting you or your household?
Discussion
Get the numbers when they move.
New data drops, indicator updates, and American Distress Index changes — delivered when it matters. No spam.
or Create an Account for full access
Loading comments…