Quarterly benchmark
MBA FHA delinquency
11.79% Q2 2026
Share of FHA loans that are at least one payment past due, excluding loans in foreclosure.
Also tracked as The FHA Signal
11.79% of FHA loans in MBA's survey at least one payment behind
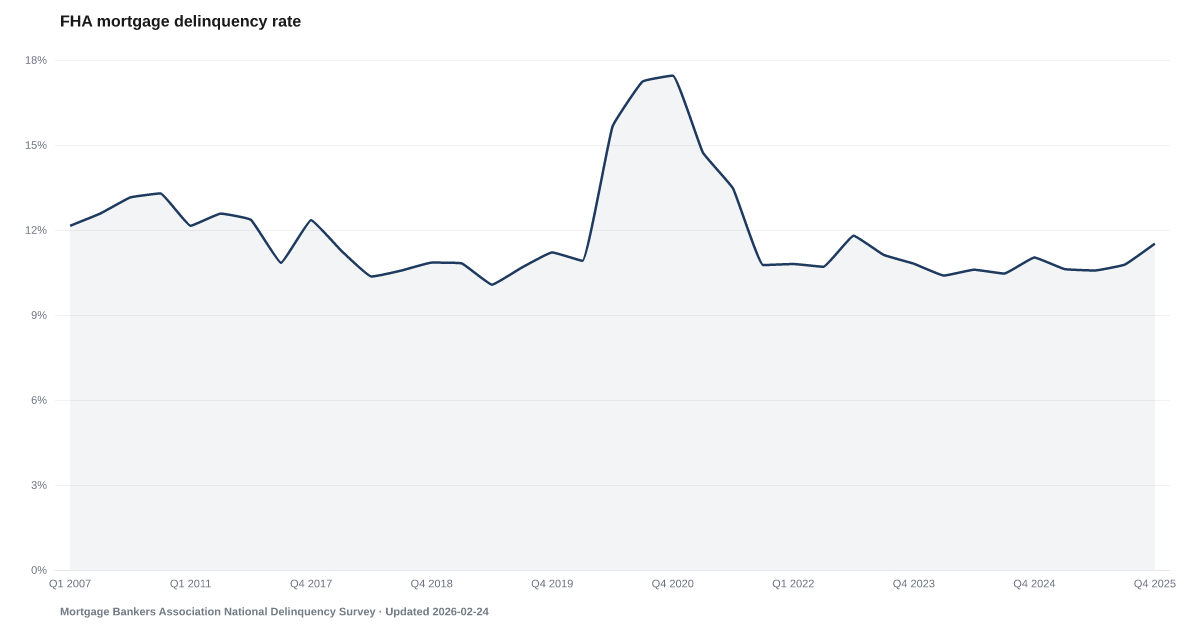
FHA mortgage delinquency was 11.79% in Q2 2026, according to the Mortgage Bankers Association, little changed from 11.88% in Q1 2026. That is the share of FHA loans in MBA's survey that were at least one payment behind at the end of the quarter, not counting loans already in foreclosure. Source: MBA National Delinquency Survey (Q2 2026).
The Mortgage Bankers Association's National Delinquency Survey put the share of FHA loans at least one payment behind at 11.79% in Q2 2026, little changed from 11.88% in Q1 2026. That is higher than the 10.57% of a year earlier.
Reporting rules move this rate as well as hardship. Loans in a payment pause, or forbearance, counted as delinquent in 2020 and 2021 when payments were not made under the original terms. From late 2025, FHA loans on a required trial payment plan count as delinquent until a permanent change to the loan is in place, and MBA says the end of pandemic-era FHA relief options in September 2025 also affected its results.
The rate counts loans, not people, and covers the FHA loans serviced by the roughly 75 companies in MBA's voluntary survey, not every FHA loan. It is a snapshot on the last day of the quarter and leaves out loans already in foreclosure. A late loan is not a foreclosure: MBA has said loans 30 or 60 days late have historically caught up at a much higher rate than loans further behind.
The U.S. Department of Housing and Urban Development publishes its own monthly FHA figure, which covers every active FHA loan and includes loans in foreclosure, so its numbers differ from MBA's. The total delinquency rate tracks late payments across all household debt, and the foreclosure filings page tracks foreclosure activity.
Is this happening to you?
Are you struggling to keep up with your mortgage payment?

MBA supplies the quarterly industry benchmark and headline. The U.S. Department of Housing and Urban Development (HUD), through the Federal Housing Administration, supplies the monthly FHA portfolio monitor. The definitions and seasonal treatment differ, so the observations are displayed together but never joined into one line.
Share of FHA loans that are at least one payment past due, excluding loans in foreclosure.
Share of active loans that are 30 or more days past due, including loans in foreclosure or bankruptcy.
| Period | Value | YoY Change |
|---|---|---|
| Jul 2026 | 13.29% | +1.11 pp |
| Jun 2026 | 13.7% | +1.55 pp |
| May 2026 | 13.49% | +1.87 pp |
| Apr 2026 | 13.09% | — |
| Mar 2026 | 13.23% | — |
| Feb 2026 | 14.19% | — |
| Jan 2026 | 13.77% | — |
| Dec 2025 | 13.97% | — |
| Nov 2025 | 13.74% | — |
| Oct 2025 | 12.04% | — |
| Sep 2025 | 12.56% | — |
| Aug 2025 | 12.51% | — |

| Period | FHA Mortgage Delinquency Rate | Bank-Booked Single-Family Mortgage Delinquency |
|---|---|---|
| Q2 2026 | 11.79% | 1.86% |
| Q1 2026 | 11.88% | 1.88% |
| Q4 2025 | 11.52% | 1.79% |
| Q3 2025 | 10.78% | 1.78% |
| Q2 2025 | 10.57% | 1.78% |
| Q1 2025 | 10.62% | 1.77% |
| Q4 2024 | 11.03% | 1.77% |
| Q3 2024 | 10.46% | 1.74% |
| Q2 2024 | 10.6% | 1.73% |
| Q1 2024 | 10.39% | 1.71% |
| Q4 2023 | 10.81% | 1.7% |
| Q3 2023 | 9.5% | 1.72% |
| Q2 2023 | 8.95% | 1.72% |
| Q1 2023 | 9.27% | 1.74% |
| Q4 2022 | 10.61% | 1.79% |
| Q3 2022 | 8.52% | 1.84% |
| Q2 2022 | 8.85% | 1.96% |
| Q1 2022 | 9.58% | 2.09% |
| Q4 2021 | 10.76% | 2.29% |
| Q3 2021 | 11.34% | 2.3% |
| Q2 2021 | 12.77% | 2.47% |
| Q1 2021 | 14.67% | 2.68% |
| Q4 2020 | 14.65% | 2.75% |
| Q3 2020 | 15.59% | 2.84% |
| Q2 2020 | 15.65% | 2.54% |
| Q1 2020 | 9.69% | 2.35% |
| Q4 2019 | 8.38% | 2.34% |
| Q3 2019 | 8.22% | 2.44% |
| Q2 2019 | 9.22% | 2.6% |
| Q1 2019 | 8.93% | 2.69% |
| Q4 2018 | 8.65% | 2.83% |
| Q3 2018 | 8.96% | 2.98% |
| Q2 2018 | 8.7% | 3.22% |
| Q3 2017 | 9.4% | 3.64% |
| Q2 2017 | 7.94% | 3.68% |
| Q1 2017 | 8.09% | 3.91% |
| Q4 2016 | 9.02% | 4.14% |
| Q3 2016 | 8.3% | 4.38% |
| Q2 2016 | 8.46% | 4.58% |
| Q3 2015 | 8.91% | 5.41% |
| Q2 2015 | 9.01% | 5.81% |
| Q1 2015 | 9.1% | 6.22% |
| Q4 2014 | 9.73% | 6.52% |
| Q4 2011 | 12.36% | 10.25% |
| Q2 2011 | 12.62% | 10.55% |
| Q1 2011 | 12.03% | 10.37% |
| Q2 2010 | 13.29% | 11.08% |
| Q1 2010 | 13.15% | 11.48% |
| Q2 2007 | 12.58% | 2.29% |
| Q1 2007 | 12.15% | 2.08% |
FHA mortgages serve many borrowers conventional lenders often decline: first-time buyers, lower-income households, borrowers with credit scores as low as 580, and those who can only afford the 3.5% minimum down payment.
A borrower who misses a payment enters 30-day delinquency. If they cannot catch up, they progress to 60-day, then 90+ day (serious delinquency). At 120 days the servicer is first allowed to start foreclosure — under federal rules that is the earliest the first filing can be made, not a point at which help arrives on its own. A servicer's duty to review you for options begins when you apply for it. If no workout is agreed, the loan can go to foreclosure; how long that takes depends on the state. The current delinquency rate, shown above, sits at the front end of the loss-mitigation and foreclosure process.
In Q1 2007, FHA delinquency in MBA's survey stood at 12.15%. The Federal Reserve bank-booked single-family mortgage rate was 2.08% that quarter and 11.48% by Q1 2010. The two series measure different things: MBA's FHA rate counts loans at least one payment behind, while the Fed's rate is the share of loan dollars on commercial banks' books 30 or more days past due, including FHA and VA loans. The gap between them is not a like-for-like comparison.
FHA loans are a minority of the outstanding mortgage market by count but account for a disproportionate share of delinquencies. When the MBA reports its blended national delinquency rate, FHA's much higher rate is folded into lower-rate loan segments rather than shown as the whole market. The separate Federal Reserve bank-booked single-family mortgage series, shown above, is lower still, underscoring how much the headline mortgage picture depends on which borrowers and servicers are in view. The American Distress Index uses FHA delinquency as supporting evidence for the Delinquency domain because it shows the FHA segment on its own rather than folded into the blended rate.
The quarterly headline comes from the Mortgage Bankers Association (MBA) National Delinquency Survey (NDS), the industry benchmark for mortgage performance. The MBA measure is seasonally adjusted and covers FHA loans at least one payment past due while excluding loans in foreclosure. The monthly portfolio monitor comes from HUD's FHA Single-Family Loan Performance Trends reports. HUD's All Past Due measure is not seasonally adjusted and covers active FHA single-family forward loans at least 30 days past due, including loans in foreclosure and bankruptcy. The two series are displayed separately and are never appended to each other. The comparison mortgage delinquency data comes from the Federal Reserve Board of Governors data retrieved via FRED (series DRSFRMACBS), covering single-family residential mortgages booked in domestic offices at all commercial banks. Historical gaps in the MBA series reflect quarters where a verified public NDS observation is not available; the full NDS dataset requires an MBA subscription.
These are delinquency scores from our County Distress Index, not county readings of FHA Mortgage Delinquency Rate.
Explore all 3,144 counties →| Period | Value | YoY Change |
|---|---|---|
| Q2 2026 | 11.79% | +1.22 pp |
| Q1 2026 | 11.88% | +1.26 pp |
| Q4 2025 | 11.52% | +0.49 pp |
| Q3 2025 | 10.78% | +0.32 pp |
| Q2 2025 | 10.57% | -0.03 pp |
| Q1 2025 | 10.62% | +0.23 pp |
| Q4 2024 | 11.03% | +0.22 pp |
| Q3 2024 | 10.46% | +0.96 pp |
| Q2 2024 | 10.6% | +1.65 pp |
| Q1 2024 | 10.39% | +1.12 pp |
| Q4 2023 | 10.81% | +0.2 pp |
| Q3 2023 | 9.5% | +0.98 pp |
The FHA mortgage delinquency rate was 11.79% in Q2 2026, according to the Mortgage Bankers Association's National Delinquency Survey, little changed from 11.88% in Q1 2026. That is higher than the 10.57% of a year earlier.
No. Loans already in foreclosure are counted separately, and MBA has said loans 30 or 60 days late have historically caught up at a much higher rate than loans further behind. Under federal rules the company you pay, called the servicer, cannot make the first foreclosure filing until a loan is more than 120 days late. A servicer's duty to review you for help options begins when you apply for it.
FHA loans carry loss mitigation options that a servicer can offer, including repayment plans, forbearances, standalone partial claims, standalone loan modifications, combination loan modifications with partial claims, and Payment Supplement. HUD runs a free housing counselor hotline at 1-800-569-4287. American Default Research's foreclosure prevention guide at americandefault.org/help/foreclosure/stop-foreclosure/ walks through the steps.
The Mortgage Bankers Association's quarterly National Delinquency Survey, a voluntary survey of about 75 mortgage servicers. HUD's monthly Single-Family Loan Performance Trends report is a separate measure that includes loans in foreclosure; the two are shown separately and never joined.
Quick poll
Is this affecting you or your household?
New data drops, indicator updates, and American Distress Index changes — delivered when it matters. No spam.
or Create an Account for full access


Loading comments…