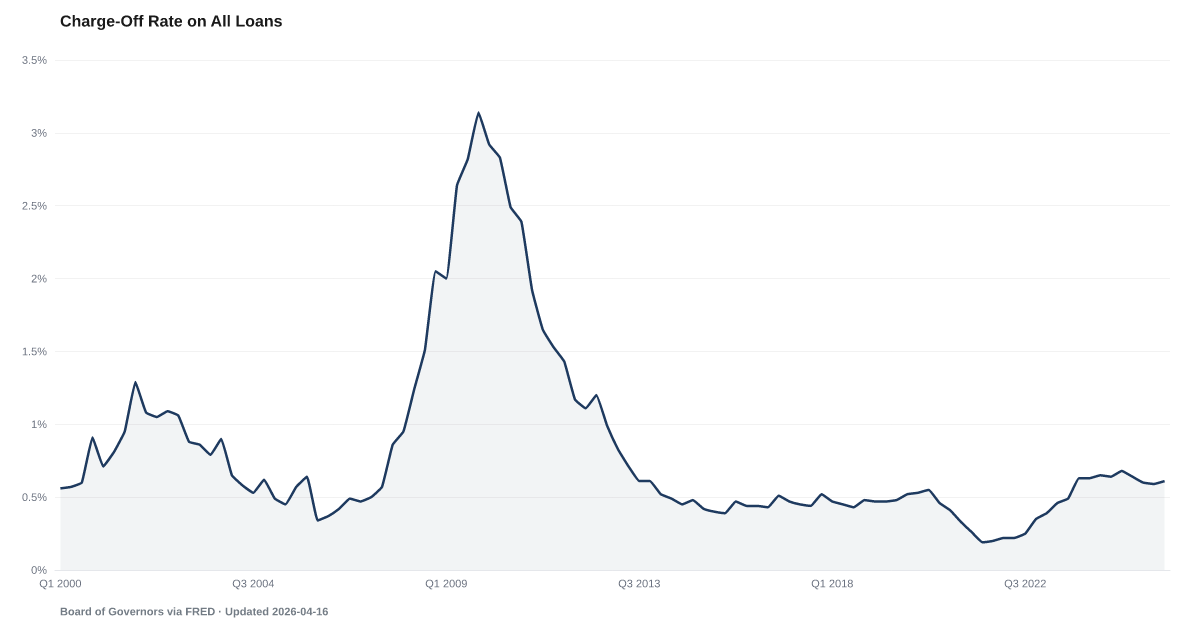
Charge-Off Rate on All Loans
Business and household loans banks wrote off, net of recoveries
In our research, this measure and Charge-Off Rate on Single-Family Residential Mortgages have tended to move in the same quarters. How we tested this
What is the current Charge-Off Rate on All Loans reading?
The net charge-off rate on all loans and leases at U.S. commercial banks was 0.55% in Q2 2026, down from 0.6% in Q2 2025, according to the Board of Governors of the Federal Reserve System. It is stated as an annual rate and is net of recoveries, and it covers business and household loans together. Source: Federal Reserve Board data retrieved via FRED (CORALACBN), not seasonally adjusted.
Commercial banks wrote off loans at an annualized net rate of 0.55% in Q2 2026, down from 0.6% in Q2 2025, the lowest unadjusted rate since Q3 2023, when it was 0.49%.
The Federal Reserve Board's net charge-off rate on all loans and leases at insured U.S.-chartered commercial banks was 0.55% in Q2 2026. That is lower than in Q2 2025, when it was 0.6%. It is the lowest unadjusted rate since Q3 2023, when it was 0.49%.
The rate has been below its level of a year before for five quarters in a row. The Board revises past quarters without a published policy, so the newest reading can still change slightly.
A charge-off is an accounting step, not the end of collection. Banks remove a loan from their books and charge it against their loss reserves, and money they later recover on it is subtracted, so this is a net figure. The rate takes a quarter's net charge-offs as a share of average loans outstanding and multiplies by four to state it as an annual rate. The quarter's own net write-offs are about one-quarter of the published figure.
The total mixes business and household lending: home and commercial real estate loans, consumer loans, business loans, farm loans and leases. Credit unions, savings institutions and nonbank lenders are outside it, and it counts dollars, not borrowers. Bank regulators' policy sets the timing for retail loans: a loss is recorded once the bank knows of it, and no later than 120 days past due for closed-end loans or 180 days for open-end loans such as credit cards. So a quarter's charge-offs can include loans that stopped paying months earlier.
The Board also publishes a seasonally adjusted version, which removes the regular calendar pattern in charge-offs. This page uses the unadjusted table, where the fourth quarter usually prints above the third, so it compares each quarter with the same quarter a year earlier. It is not a bankruptcy measure: bankruptcy is only one reason a loan is charged off, and court filings are counted in the bankruptcy filings page. The same Fed release gives separate rates by loan type, including Credit Card Charge-Offs and Mortgage Charge-Offs.
Explore Further
Charge-Off Rate on All Loans over time: what has changed?

Counties with the highest default and legal scores
These are default and legal scores from our County Distress Index, not county readings of Charge-Off Rate on All Loans.
Explore all 3,144 counties →| Period | Value | YoY Change |
|---|---|---|
| Q2 2026 | 0.55% | -0.05 pp |
| Q1 2026 | 0.57% | -0.07 pp |
| Q4 2025 | 0.61% | -0.07 pp |
| Q3 2025 | 0.59% | -0.05 pp |
| Q2 2025 | 0.6% | -0.05 pp |
| Q1 2025 | 0.64% | +0.01 pp |
| Q4 2024 | 0.68% | +0.05 pp |
| Q3 2024 | 0.64% | +0.15 pp |
| Q2 2024 | 0.65% | +0.19 pp |
| Q1 2024 | 0.63% | +0.24 pp |
| Q4 2023 | 0.63% | +0.28 pp |
| Q3 2023 | 0.49% | +0.24 pp |
Frequently Asked Questions
What is the current charge-off rate on all bank loans?
In Q2 2026, insured U.S.-chartered commercial banks charged off 0.55% of their average loans and leases at an annual rate, net of recoveries, down from 0.6% in Q2 2025. The figure is the Federal Reserve Board's unadjusted series, FRED code CORALACBN.
Is the rate the share of loans lost in one quarter?
No. The Board multiplies each quarter's net charge-off ratio by 400 to state it as an annual percentage rate. The quarter's own net write-offs are about one-quarter of the published figure.
Is this a bankruptcy rate?
No. It is a dollar ratio of loans banks wrote off, not a count of people or court filings. Bank regulators' policy sends loans to charge-off when they fall far enough past due as well as after a bankruptcy notice, and the Fed does not split charge-offs by cause.
Where does this data come from?
The Federal Reserve Board compiles it from the quarterly Call Reports that commercial banks file and publishes it about two months after each quarter ends, with no fixed release date. FRED republishes the unadjusted series as CORALACBN.


Quick poll
Is this affecting you or your household?
Discussion
Get the numbers when they move.
New data drops, indicator updates, and American Distress Index changes — delivered when it matters. No spam.
or Create an Account for full access
Loading comments…