Serious Delinquency Rate, Fannie Mae and Freddie Mac Loans
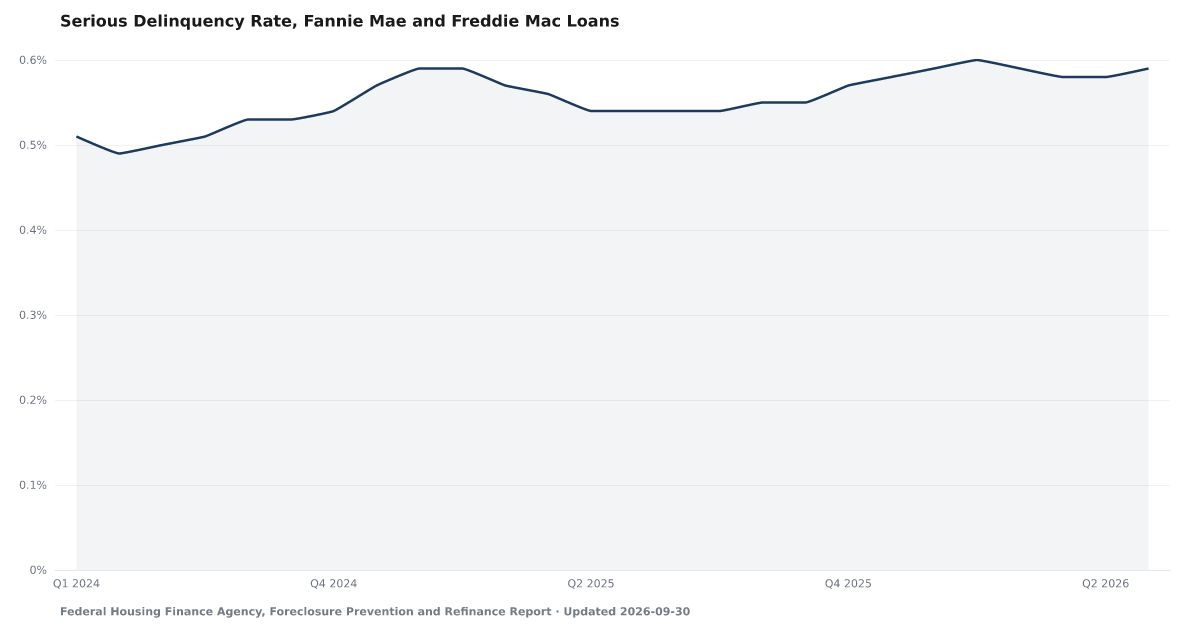
Fannie Mae and Freddie Mac loans 90 or more days behind or in foreclosure, share by month
What is the current Serious Delinquency Rate, Fannie Mae and Freddie Mac Loans reading?
The serious delinquency rate on Fannie Mae and Freddie Mac loans was 0.59% at the end of June 2026, up from 0.54% a year earlier. It is the share of the single-family loans the two companies service that are 90 or more days behind or in foreclosure. FHA, VA and bank-portfolio loans are not included. Source: Federal Housing Finance Agency, Foreclosure Prevention and Refinance Report.
Measurement basis: Percent of all Fannie Mae and Freddie Mac single-family loans serviced that are 90 days or more delinquent or in the process of foreclosure, at month end (FHFA's glossary: loans three or more payments behind, including loans in bankruptcy, plus all loans in foreclosure). A share of loans, not of balances, and only the two companies' conventional book, not FHA, VA or bank-portfolio loans. Read from the Mortgage Performance table on the Highlights page of FHFA's Foreclosure Prevention and Refinance Report; a quarter-end month is published from the quarterly edition when it arrives. If a later monthly edition restates it, we log the new figure for review and keep the published one. Not the NY Fed all-loan-types balance rate (serious_delinquency_rate).
Serious delinquency on Fannie Mae and Freddie Mac loans was 0.59% in June 2026, up from 0.54% a year earlier.
The Federal Housing Finance Agency, which oversees Fannie Mae and Freddie Mac, counts a loan as seriously delinquent when it is 90 or more days behind, meaning three or more missed payments, or in foreclosure. At the end of June 2026, 0.59% of the single-family loans the two companies service were in that state, up from 0.54% a year earlier.
The rate has been higher than in the same month a year earlier for five months in a row.
The count covers only single-family loans that Fannie Mae or Freddie Mac own or guarantee. FHA, VA and bank-portfolio loans are not in it. For a rate across every kind of household debt, measured by balance each quarter, see Serious Delinquency Rate (90+ days, All Loan Types). For FHA loans, see FHA Mortgage Delinquency Rate.
FHFA publishes this report as a PDF with no release calendar, monthly for eight months of the year and quarterly for March, June, September and December. A quarter-end month's rate comes from the quarterly edition when it arrives. If a later monthly edition restates it, we log the new figure for review and keep the published one.
Explore Further
Serious Delinquency Rate, Fannie Mae and Freddie Mac Loans over time: what has changed?

Counties with the highest delinquency scores
These are delinquency scores from our County Distress Index, not county readings of Serious Delinquency Rate, Fannie Mae and Freddie Mac Loans.
Explore all 3,144 counties →| Period | Value | YoY Change |
|---|---|---|
| Jun 2026 | 0.59% | +0.05 pp |
| May 2026 | 0.58% | +0.04 pp |
| Apr 2026 | 0.58% | +0.02 pp |
| Mar 2026 | 0.59% | +0.02 pp |
| Feb 2026 | 0.6% | +0.01 pp |
| Jan 2026 | 0.59% | 0 pp |
| Dec 2025 | 0.58% | +0.01 pp |
| Nov 2025 | 0.57% | +0.03 pp |
| Oct 2025 | 0.55% | +0.02 pp |
| Sep 2025 | 0.55% | +0.02 pp |
| Aug 2025 | 0.54% | +0.03 pp |
| Jul 2025 | 0.54% | +0.04 pp |
Frequently Asked Questions
What does seriously delinquent mean here?
FHFA counts a loan as seriously delinquent when the borrower is 90 or more days behind, meaning three or more missed payments, or when the loan is in foreclosure. Loans in bankruptcy that are that far behind count too.
Does this rate cover every mortgage?
No. It covers only single-family loans owned or guaranteed by Fannie Mae and Freddie Mac. FHA, VA and bank-portfolio loans are not in it.
How is this different from the New York Fed's serious delinquency rate?
The New York Fed's rate covers every kind of household debt, including credit cards, auto loans and student loans, and measures the share of balances once a quarter. This one counts Fannie Mae and Freddie Mac mortgage loans each month.
Where does this data come from?
The Federal Housing Finance Agency's Foreclosure Prevention and Refinance Report, which FHFA publishes as a PDF with no release calendar: a monthly edition for eight months of the year and a quarterly edition for March, June, September and December. We read the Highlights table of each new edition with an automated parser and check every number against the PDF's own text before it is saved.

Quick poll
Is this affecting you or your household?
Discussion
Get the numbers when they move.
New data drops, indicator updates, and American Distress Index changes — delivered when it matters. No spam.
or Create an Account for full access
Loading comments…